Guides
Covering a moving company: insurance types and typical premiums
Moving company policies cover released value, full value protection, and separate cargo insurance, explaining typical premiums and why valuation is liability.
What to take away
- For a moving company, valuation is not insurance. Valuation is the carrier's liability for the customer's goods under the rules that govern the move. Insurance is a policy the carrier buys for its own risks.
- A mover carries five core policiescommercial auto, cargo, general liability, workers' compensation and property. Umbrella or excess sits above them, and exclusions matter more than limits.
- Typical premiums are quoted per exposure, not per policy. Auto runs on power units and driver records, cargo on declared value of goods handled, general liability on payroll and revenue, workers' compensation on payroll by class code.
- Planning figures for a one-to-three-truck carrierauto $8,000 to $15,000 per power unit, cargo $1,500 to $6,000, general liability $2,000 to $8,000, workers' compensation $4 to $12 per $100 of payroll, property $1,200 to $5,000.
- Required minimums come from FMCSA for interstate moves and the state regulator for intrastate ones. The figures here are planning ranges, and your quote comes from an underwriter who writes household-goods carriers.
Valuation first, because customers ask about it first
When a customer asks "are you insured," they usually mean "what happens if you break my table." The answer is valuation: the level of liability the mover takes on for loss or damage to the goods. The customer chooses from the options the governing rules provide, priced on the estimate.
Interstate rules set two of them. Released value pays 60 cents per pound per article, so a 40-pound chair that cost $600 returns $24. Full value protection repairs, replaces or pays the current value of the item, and carriers must offer it with a federal floor of $6.00 per pound per article.
For interstate moves, the Federal Motor Carrier Safety Administration sets the options and disclosures. Its Protect Your Move materials describe the loss-and-damage information a customer is entitled to. For intrastate moves, the state regulator sets the options, if it sets any.
Do not state the valuation options from memory on your website or your estimate. Use the regulator's wording, offer the choices it requires, and record the customer's selection. The licensing and compliance guide explains how to identify which regulator's rules apply to your moves.
What each policy costs
These ranges are planning figures for a small household-goods carrier running one to five power units. Treat them as a starting point for a conversation with an agent, not as a quote.
Illustrative annual premiums
- Commercial auto liability$8k–$15k/unit
- Cargo$1,500–$6,000
- General liability$2,000–$8,000
- Workers' comp$4–$12/$100
- Property$1,200–$5,000
- Umbrella or excess$1.5k–$6k/$1M
| Coverage | Illustrative annual premium | What drives the number |
|---|---|---|
| Commercial auto liability | $8,000 to $15,000 per power unit | Driver records, radius, vehicle weight, loss runs |
| Auto physical damage | $2,000 to $6,000 per power unit | Vehicle value and age, radius, comprehensive and collision deductibles |
| Cargo | $1,500 to $6,000 | Declared value handled, radius, commodity, deductible |
| General liability | $2,000 to $8,000 | Payroll, revenue, storage exposure, premises |
| Workers' compensation | $4 to $12 per $100 of payroll | Class code, state rate, experience modifier |
| Property | $1,200 to $5,000 | Building value, contents, equipment schedule, deductible |
| Warehouse legal liability, sometimes called bailee coverage | $1,000 to $4,000 | Value of goods in storage, square footage, security, deductible |
| Umbrella or excess | $1,500 to $6,000 per $1M | Underlying limits and the losses behind them |
| Federal filings on Form BMC-91X and Form BMC-32 | No separate premium | Included with the auto liability and cargo policies |
The arithmetic is simple once the rating base is named. Workers' compensation premium equals payroll by class code, multiplied by the state manual rate, multiplied by your experience modifier. Cargo is usually quoted at roughly $3 to $8 per $1,000 of declared value handled.
Cargo limits for a small carrier typically run $50,000 to $250,000 per occurrence. General liability is usually written at $1 million per occurrence and $2 million aggregate, with the umbrella above it. Those limits decide how much a claim can pay, not the premium.
A crew payroll of $150,000 at $6 per $100 with a 1.0 modifier produces a $9,000 premium. The same payroll at $12 per $100 costs $18,000. Moving-and-storage class codes come from NCCI in most states, and from the state bureau in California, New York and a few others.
Sole proprietors and partners are often excluded from workers' compensation by default, so a day-rate crew can change the payroll you report. Ask the agent how each worker is classified before the policy starts.
Across all lines, a one-truck carrier with a clean loss history typically budgets $20,000 to $35,000 a year in most markets as of 2026. Three trucks push that toward $45,000 or more.
Auto is the line that moves most. A driver with a recent at-fault accident can double the unit's premium, and a radius change from 50 miles to 500 miles resets the rating class.
Household goods is specialty business, so most movers buy through an independent broker. Insureon, CoverWallet and Simply Business place these lines for small carriers.
Great West Casualty Company, Sentry Insurance, Northland Insurance, Vanliner Insurance Company and Philadelphia Insurance Companies write moving-and-storage programs. Progressive Commercial and Canal Insurance write trucking auto liability without a household-goods focus. NEXT Insurance sells small general liability policies online, and those do not replace a cargo form.
Federal floors sit below a real claim. Auto liability starts at $750,000 for vehicles rated 10,001 pounds or more, under 49 CFR 387.9. Cargo filings for household-goods carriers are commonly cited at $5,000 per vehicle and $10,000 per occurrence, filed with FMCSA on Form BMC-32.
The policies a mover carries
| Coverage | What it responds to | The exclusion to look for |
|---|---|---|
| Commercial auto liability | Injury or damage to others caused by your trucks | Drivers not listed; vehicles not scheduled; personal use |
| Cargo | Loss or damage to goods in your care, in transit and sometimes in storage | Customer-packed cartons; unattended vehicle; high-value items |
| General liability | Injury or damage at the customer's premises not arising from the vehicle | Damage to the goods themselves; work being performed |
| Workers' compensation | Injury to your employees | Misclassified workers; state-specific rules |
| Property | The yard, the warehouse, the equipment | Customer goods in storage, which may need a separate form |
| Umbrella or excess | Limits above the primary policies | Only follows the underlying policies' terms |
Which of these are required, and at what minimums, is a question for FMCSA for interstate carriers, whose regulations and enforcement page identifies the rules that govern interstate household-goods carriers, and for the state regulator for intrastate movers.
The seven-question protocol
Run these against every policy before buying and at every renewal.
Seven-question policy review
- What exactly is scheduled?
- What does cargo exclude?
- What is the deductible per occurrence?
- Does it cover goods in storage?
- What must you do after a loss?
- Who is an insured?
- What changes the premium?
- What exactly is scheduled?Every truck, every trailer, and every driver who will operate them. A truck bought mid-season and not added is an uninsured truck; the equipment checklist includes "added to policy" as a line for that reason.
- What does cargo exclude?Customer-packed cartons, items of high value per pound, goods in an unattended vehicle overnight, and goods in storage are the usual gaps.
- What is the deductible per occurrence, and how is an occurrence defined?One move with ten damaged pieces may be one occurrence or ten.
- Does the policy cover goods in storage-in-transit, and in your own warehouse?If you sell storage, the answer must be yes or you need another form, such as warehouse legal liability.
- What must you do after a loss?Notice periods, documentation, and whether the customer's claim form and your inventory are required.
- Who is an insured?Subcontracted crews and labor-only helpers may not be, and a claim involving them may be denied.
- What changes the premium?Claims history, driver records, vehicle weight, radius of operation, and interstate versus intrastate. Knowing this tells you which operating decisions are also insurance decisions.
Where insurance meets operations
Three operating habits reduce both claims and premiums, and none of them costs money:
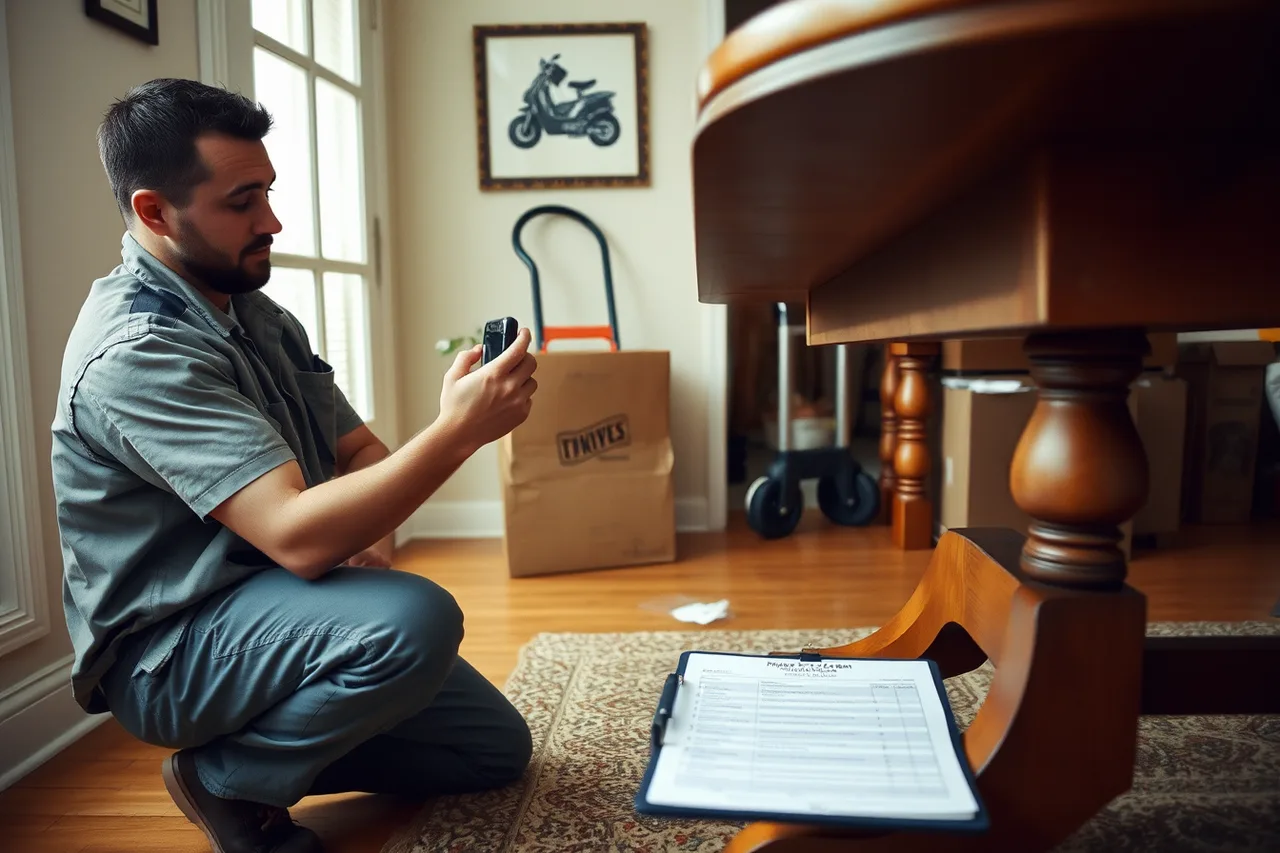
- The walkthrough with pre-existing damage photographed. It closes the claim that was not yours.
- The customer-packed carton inspection, recorded on the crew sheet. It documents the exclusion before it is invoked.
- The pre-trip inspection and the driver qualification file. The auto insurer will ask for both after an incident.
Truck size also affects insurance. Vehicles above certain weight ratings bring different requirements and different premiums. That is one more reason the equipment and setup guide treats truck weight as a business decision, not a capacity one.
The premises
If customers visit an office or a storage facility, accessibility is part of the liability picture. The U.S. Department of Justice's ADA guide for small businesses explains barrier removal, accessible routes, and service practices for existing facilities. Read it alongside the general liability policy, because an inaccessible entrance is both a compliance issue and a claim waiting to happen.
A second market, a second conversation
Insurance is priced by state and by radius. A second yard in another state, or a first interstate job, changes the underwriting.
Expect the workers' compensation piece to move first, because the new state brings its own manual rate and class code. Talk with the insurer before the decision, not after the first job. The expansion and market guide treats the insurer's answer as an input to the decision.
The licensing side of the same move, which authority requires what proof of coverage, is worked through in what licenses a moving company needs.
Common questions
Is cargo insurance the same as full-value protection?
No. Full-value protection is a valuation option the customer selects under the governing rules, and it is the mover's liability. Cargo insurance is the mover's policy that may or may not fund that liability. Ask the insurer whether it does.
What should I tell a customer who asks if I am insured?
Name the valuation options they can choose, in the regulator's words, and confirm that the company carries the coverages the regulator requires. Then show them the certificate of insurance if they ask.
Can I skip workers' compensation for helpers paid by the day?
Ask the state. Misclassification is the exclusion that turns an injury into an uninsured liability, and the state's rules decide who is an employee. A day-rate helper on a regular schedule is an employee in most states.
How much coverage do I need?
The regulator's minimum is the floor: $750,000 of auto liability for interstate trucks rated 10,001 pounds or more. Above it, the answer depends on the goods you carry and the yard's own exposure, and it is a conversation with an agent who knows household-goods carriers.